An instant cash offer for a house can be useful when you want a quick sense of your options. But the first number you see is not always the number that appears in a purchase agreement—and the contract price is not necessarily the amount that reaches your bank account after closing.
The practical question is not simply, “What is the offer?” It is: What does this number represent, what can still change it, and what will I net after every agreed deduction and property payoff?
This guide separates an early estimate from a post-walkthrough written offer, explains why property access matters, and shows how to review fees, contingencies, and expected proceeds without treating any offer or closing as guaranteed.
The Short Answer: Follow the Written Terms, Not the Fastest Number
A number generated from a short form, phone conversation, photos, or public data may be a preliminary estimate. It can help decide whether to continue, but it may rely on incomplete facts about the property’s layout, condition, occupancy, title, or remaining contents.
A written offer prepared after the buyer has gathered the information it requires is more meaningful. Even then, read the document. A written offer may expire, require acceptance, or include contingencies that permit investigation, cancellation, or a negotiated change. Once accepted, the purchase agreement and any signed amendments—not an advertisement, calculator, text message, or verbal summary—define the transaction.
At closing, escrow or title prepares a statement showing the price, credits, debits, payoffs, and amount due to the seller. California Department of Real Estate guidance explains that escrow completes the transaction after the contract conditions are met and prepares a final closing statement listing the credits and debits. That makes the settlement statement the best place to confirm expected disbursement, while the signed agreement controls what the parties promised.
Five Different Numbers Sellers Often Confuse
| Number | What it usually means | What to verify |
|---|---|---|
| Automated or instant estimate | An early range or figure based on limited property and market information. | Is it labeled an estimate, range, or offer? What assumptions does it use? |
| Preliminary buyer number | A buyer’s initial indication before completing its required property review. | What information is still missing, and can the number change after access? |
| Written offer | Proposed price and terms delivered in writing. | Expiration, buyer identity, proof of funds, contingencies, fees, deposit, and closing date. |
| Accepted contract price | The agreed purchase price after acceptance and any counters. | Which clauses or signed amendments could still change the price or allow cancellation? |
| Estimated or final seller net | What remains after contract credits/debits, property payoffs, prorations, and seller-paid costs. | Compare the preliminary statement with the final settlement statement before signing. |
Different buyers use these labels differently. Do not rely on the label alone. Ask what the document is, whether it is binding after acceptance, and which provisions survive until closing.
What an Instant Cash Offer for a House May Represent
An early buyer may begin with the address, property type, bedrooms and bathrooms, lot size, public records, nearby sales, photos, and the seller’s description. That can produce a useful starting point, but it may not answer questions such as:
- Can the buyer access every room, garage, basement, crawl space, or occupied unit?
- Does the actual layout match public records and the information supplied?
- Are visible roof, foundation, electrical, plumbing, moisture, fire, or pest concerns present?
- Will personal property, debris, or tenants remain after closing?
- Do additions, conversions, solar agreements, code notices, or other records require more review?
- Are there access, title, lien, probate, bankruptcy, or co-owner issues that could affect the transaction?
The site’s public How It Works page describes a preliminary offer followed by property assessment and a final offer. Treat that as a process distinction, not a promise that every property will receive a particular amount or follow one fixed timeline.
What a Walkthrough Can—and Cannot—Confirm
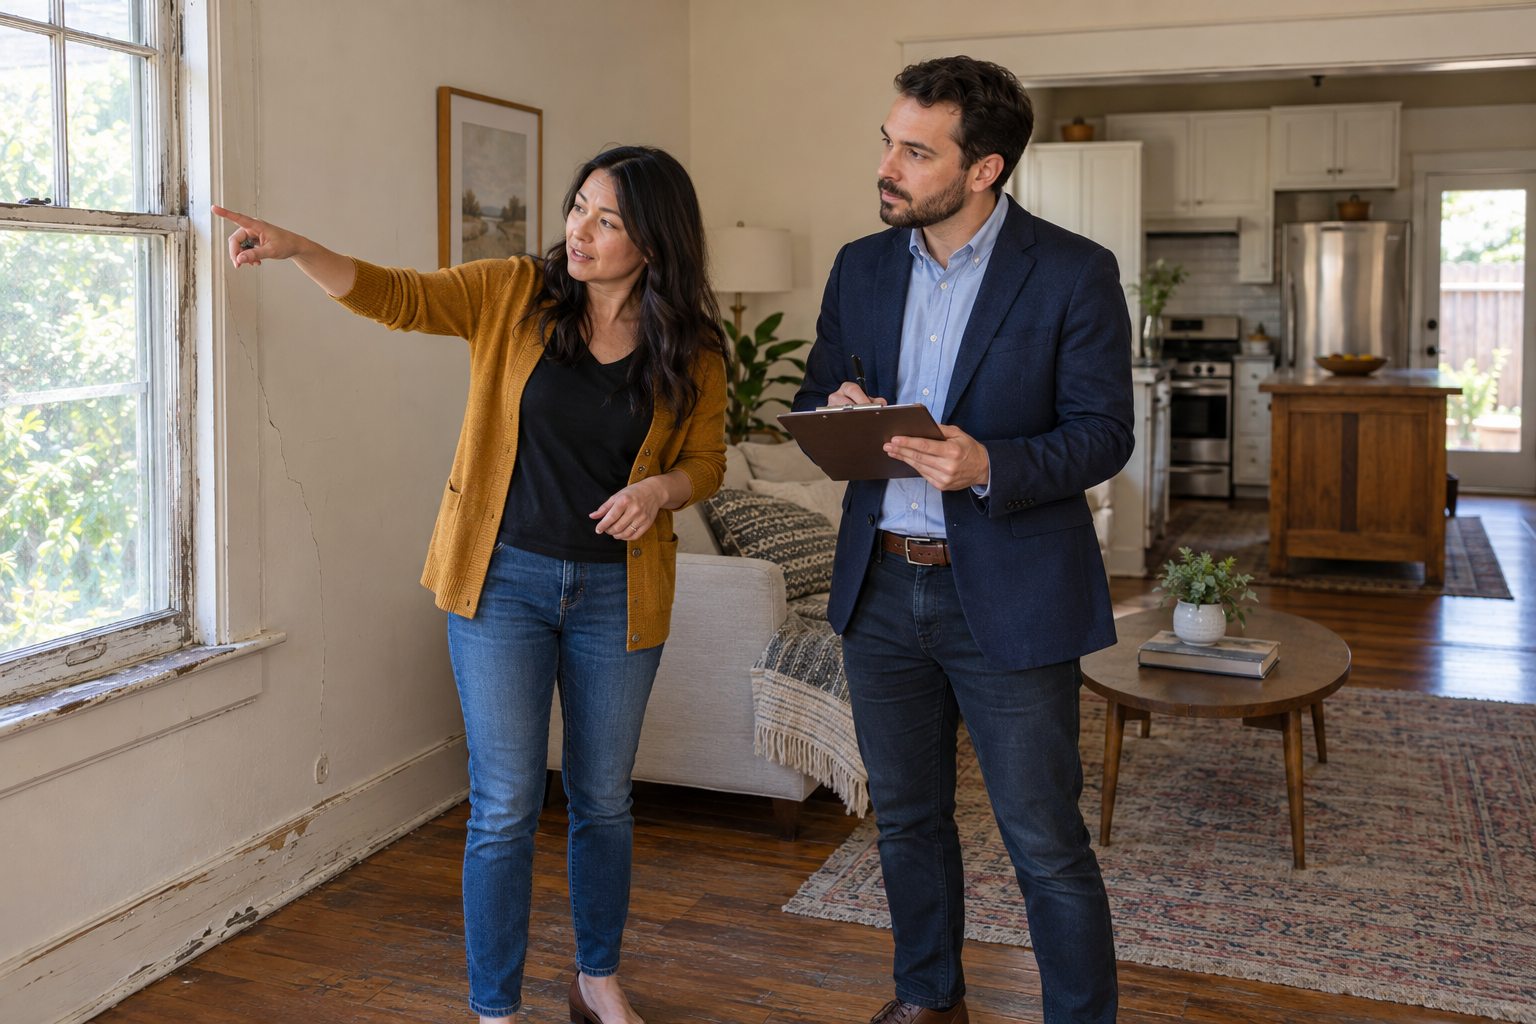
A walkthrough lets the buyer compare the property with the information used for the preliminary number. A short visit may confirm the general layout, visible condition, access, occupancy, major systems, and the amount of cleanup or work the buyer expects to handle.
A walkthrough is not automatically the same as a professional home inspection. It may not reveal concealed leaks, underground conditions, code history, title defects, or the final cost of repairs. Ask whether the visit is the buyer’s complete condition review or whether the agreement still contains a later inspection, feasibility, partner-approval, or due-diligence period.
Can the Offer Change After the Walkthrough?
It can, depending on what the first number represented and what the written terms allow. If a preliminary estimate assumed an ordinary roof and the walkthrough reveals active leaks and widespread interior damage, a buyer may issue a different written offer. A seller can accept, reject, or negotiate that new proposal unless an existing agreement says otherwise.
After a purchase agreement is accepted, the answer depends on the contract. A buyer may have an investigation or approval contingency, or the parties may sign an amendment changing the price or allocating a repair credit. California DRE guidance says contingencies and special conditions belong in the offer and contract changes should be understood before signing. For advice about a specific clause, consult a qualified California real-estate attorney or licensed professional who represents your interests.
A price reduction is not automatically justified merely because a walkthrough occurred. Ask for the exact new information, the related cost assumption, and the contract provision the buyer is using. Keep every version of the offer so you can compare the change rather than relying on a verbal explanation.
Hypothetical Example: From Preliminary Estimate to Closing Net
The following figures are entirely hypothetical. They are not a We Buy Properties in Bay Area offer, fee schedule, formula, customer result, or guarantee.
| Stage | Hypothetical amount | What changed |
|---|---|---|
| Preliminary estimate | $720,000 | Based on the address, seller description, public data, and selected photos. |
| Post-walkthrough written offer | $690,000 | The buyer documents a roof leak, damaged subfloor, and more remaining contents than assumed. |
| Accepted contract price | $690,000 | The seller accepts after reviewing the price, contingencies, costs, and closing date. |
| Signed amendment | $690,000 | No price change; the parties document which personal property may remain. |
The $30,000 difference deserves an explanation. It does not prove the first number was deceptive or the second number was correct. The seller should review whether the newly identified conditions are real, whether the cost allowance is reasonable, and whether another buyer would treat them differently.
Now separate the contract price from the seller’s expected proceeds:
| Hypothetical seller-net item | Amount |
|---|---|
| Accepted purchase price | $690,000 |
| Less: mortgage payoff | ($372,000) |
| Less: recorded lien payoff | ($7,500) |
| Less: delinquent property taxes | ($4,200) |
| Less: tax, rent, utility, or other prorations | ($1,800) |
| Less: seller-paid service or transaction fee | $0 in this example only |
| Less: seller-paid title, escrow, transfer, or recording costs | $0 in this example only |
| Estimated seller net | $304,500 |
The arithmetic is $690,000 − $372,000 − $7,500 − $4,200 − $1,800 = $304,500. The two zero-dollar rows are assumptions for this example—not verified universal business terms. If a real agreement assigns a service fee, repair credit, closing cost, transfer charge, or other debit to the seller, the estimated net must reflect it.
Deductions, Fees, and Contingencies to Check
Price adjustments and repair credits
Check whether the buyer can cancel or seek a change after a walkthrough, inspection, document review, contractor visit, or internal approval. A legitimate contract change should appear in writing. Do not assume a verbal “final number” overrides a contingency or amendment.
Service, assignment, transaction, or cancellation fees
Ask whether the buyer or an affiliated party charges any fee outside the purchase price. Search the agreement and addenda for terms such as service fee, transaction fee, administrative fee, assignment, marketing, cancellation, processing, or seller charge. The FTC has challenged misleading claims about home-sale costs and seller proceeds in another company’s marketing; the useful lesson is to compare the written net, not a headline number.
Closing-cost allocation
“No fees” and “buyer pays closing costs” can mean different things in different agreements. Identify who pays escrow, title insurance, transfer taxes, recording, notary, document, HOA, municipal, and other transaction charges. Ask escrow or title to reflect the allocation in a preliminary seller statement.
Property payoffs and prorations
A mortgage payoff, HELOC, recorded lien, delinquent tax, HOA balance, judgment, or other title item can reduce proceeds even when it does not change the buyer’s price. Property taxes, rents, utilities, deposits, or other amounts may also be prorated. Ask which figures are estimates and when the final payoff statements will arrive.
Buyer contingencies and approval rights
Cash removes a buyer mortgage from the transaction only if the buyer is truly using available cash. It does not automatically remove inspection, title, access, partner, feasibility, document-review, or other contingencies. Request proof of funds and identify every clause that lets the buyer cancel, delay, or request new terms.
Which Number Actually Holds Up at Closing?
The most dependable price is the one in the current signed purchase agreement, as modified by any signed amendments and subject to the agreement’s unresolved contingencies. The most dependable proceeds figure is the final settlement statement after escrow has current payoffs, prorations, credits, and charges.
Neither figure guarantees that closing will occur. Title defects, missing signatures, unmet conditions, fraud concerns, court or lender requirements, buyer default, casualty damage, or another contract issue can delay or prevent closing. Read the agreement, verify instructions independently with escrow or title, and do not make irreversible moving or financial commitments based only on an early estimate.
If you are comparing sale routes, review cash buyer versus Realtor for a Bay Area home sale. Once an agreement is accepted, the guide to what happens after accepting a cash offer explains the broader closing sequence.
A Seller’s Before-Signing Checklist
- Label the number. Is it an automated estimate, preliminary range, written offer, counteroffer, or accepted contract price?
- Confirm the buyer. Identify the person or legal entity signing and ask for current proof of funds.
- Ask what remains unverified. Confirm whether another walkthrough, inspection, contractor visit, document review, or partner approval is planned.
- Mark every contingency. Note the deadline, removal method, cancellation right, and effect on the deposit.
- List every seller cost. Include fees, credits, repairs, title and escrow items, transfer charges, prorations, and personal-property obligations.
- Request a seller-net estimate. Give escrow or title enough information to estimate mortgage, lien, tax, HOA, and other payoffs.
- Compare versions. Keep the instant number, written offer, counters, amendments, and settlement statements together.
- Confirm dates separately. Offer expiration, contingency deadlines, signing, closing, recording, possession, and move-out are not interchangeable.
- Get independent advice when needed. Use a qualified attorney, tax professional, escrow/title contact, or licensed real-estate professional for property-specific questions.
Frequently Asked Questions
Is an instant cash offer for a house binding?
Not necessarily. An online or verbal number may be only an estimate or preliminary indication. Whether a written offer becomes binding depends on the document, acceptance, applicable law, and its terms. Read the agreement and obtain property-specific advice if anything is unclear.
Can a cash offer change after a walkthrough?
Yes, if the earlier figure was preliminary or if the contract permits further investigation or negotiation. Ask before granting access whether the number can change, what the walkthrough will cover, and whether any later inspection or approval contingency remains.
Can a buyer deduct repair costs at closing?
Repair costs should be reflected in the agreed price, a credit, or another written term. A seller should question any unexpected closing deduction and ask escrow, title, and an appropriate adviser to identify the supporting agreement or signed amendment.
Does the written cash offer equal my final proceeds?
No. The offer states a proposed purchase price and other terms. Mortgage and lien payoffs, delinquent taxes, prorations, credits, and any seller-paid fees or closing costs can reduce the amount disbursed. Request a preliminary seller-net statement and review the final settlement statement.
How do I get a cash offer on my house from We Buy Properties in Bay Area?
Use the site’s cash-offer contact form or call or text the number shown there. Share what you know about the property and ask whether the first number is preliminary, what access or documents are still needed, and when you will receive complete written terms. Requesting an offer does not require you to accept it.
Get a Property-Specific Offer and Compare the Net
If you are thinking, “I want to get a cash offer on my house,” start by giving the buyer accurate information and asking how the process moves from an early number to written terms. A useful cash offer for my house is one I can compare after price, contingencies, costs, payoffs, and timing are all visible.
The existing contact process is free and carries no obligation to accept. Ask whether the first We Buy Properties in Bay Area offer is preliminary, review any later written offer line by line, and compare the expected seller net before deciding.